Inflation is not just an economic number released by the government. It affects the amount households spend on groceries, electricity, transport, housing and everyday services. Even a relatively small monthly increase can put pressure on a budget when several essential expenses rise together.
The latest US Consumer Price Index (CPI) report, released on November 10, 2026, showed that consumer prices increased by 0.4% in October on a seasonally adjusted basis. Food prices rose 0.5%, while energy prices increased 0.7%. The index for all items excluding food and energy increased 0.3%.
These figures do not mean every household experienced the same increase. Your personal cost of living depends on where you live, what you buy, your housing arrangements and how much of your income goes towards essential expenses.
Here is what the latest inflation report means for household finances and how you can respond.
What happened to US inflation in October 2026?
According to the US Bureau of Labor Statistics, the Consumer Price Index for All Urban Consumers increased 0.4% in October, following a 0.6% increase in September.
Some important changes included:
- Food prices increased 0.5%.
- Food purchased for home consumption increased 0.4%.
- Restaurant and other food-away-from-home prices increased 0.5%.
- Energy prices increased 0.7%.
- Shelter costs increased 0.3%.
- Core CPI, which excludes food and energy, increased 0.3%.
One important limitation needs explaining. Because the Bureau of Labor Statistics did not collect October 2025 survey data during a lapse in appropriations, it could not publish the usual 12-month percentage change for many October 2026 CPI measures.
That means readers should avoid treating an estimated annual inflation figure as an official BLS year-over-year result for this release.
Why do these price changes matter to households?
1. Grocery bills can become harder to control
Food prices increased 0.5% in October. The increase may appear modest, but groceries are a recurring expense. Families cannot simply stop buying essential food when prices rise.
A household spending $700 per month on groceries would need to spend approximately $3.50 more if its own basket increased by 0.5%. This is an illustration, not a prediction of what every household will pay.
The more useful approach is to review actual receipts and identify which products are becoming more expensive.
2. Energy costs affect more than utility bills
Energy prices increased 0.7% in October after a much larger increase in September. Energy costs can influence household budgets directly through electricity, heating and fuel.
They can also affect businesses’ operating and transportation expenses. Over time, some of those costs may be reflected in the prices consumers pay for goods and services. For a closer look at how fuel feeds through to other prices, see our analysis of rising oil prices and household costs.
The impact differs by region, season, home type and transport habits.
3. Housing remains a major budget consideration
Shelter costs increased 0.3% in October. Housing is often one of the largest monthly expenses, especially for renters and households with mortgages.
When housing costs rise, there may be less room in a budget for saving, debt repayment or discretionary spending.
How can inflation affect interest rates?
Inflation is one of the factors the Federal Reserve considers when setting monetary policy. If price increases remain persistent, policymakers may decide that interest rates need to stay higher for longer or change in response to economic conditions.
However, one monthly CPI report does not automatically determine the next Federal Reserve decision.
Interest rates also influence personal finances in different ways:
- Variable-rate debt may become more expensive when borrowing rates rise.
- New mortgage borrowers may face higher financing costs.
- Credit card balances can become harder to repay.
- Savers may receive better returns on some interest-bearing accounts.
The actual impact depends on the financial product and its terms.
Five practical ways to manage a rising cost of living
1. Review your actual spending
Look at the last two or three months of bank and card statements. Separate essential spending from optional purchases.
Do not rely only on a budget you created months ago. Use real spending records to identify where costs have changed. If you need a starting structure, this realistic single-adult budget shows how the main categories fit together.
2. Create a flexible grocery plan
Plan meals before shopping, compare unit prices and check whether store brands offer similar quality.
Buying in bulk is not automatically cheaper if products expire before you use them.
3. Review recurring subscriptions
Streaming services, memberships, apps and unused subscriptions can quietly consume part of a monthly budget.
Cancel services you no longer use and compare renewal prices before accepting automatic increases.
4. Protect your emergency savings
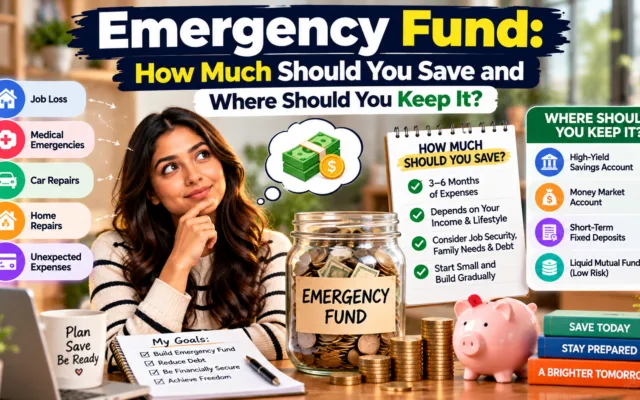
An emergency fund can help cover unexpected costs without relying entirely on credit cards or expensive borrowing.
If saving a large amount feels difficult, begin with a manageable regular contribution and build gradually. Our guide to building an emergency fund walks through a simple monthly plan.
5. Review high-interest debt
List outstanding balances, interest rates and minimum payments. Prioritise a repayment strategy that reduces expensive debt while keeping essential bills current.
Avoid taking on new debt simply to maintain discretionary spending.
A simple example: Why small increases add up
Imagine a household spends $3,000 each month on its regular expenses. If its own spending basket becomes 0.4% more expensive, the additional cost would be $12 per month.
That calculation is only an illustration. The official CPI measures average price changes across a broad basket, not the exact inflation rate experienced by an individual household.
The important lesson is to measure your own expenses rather than assuming the national figure precisely matches your personal situation.
What should households watch next?
The next US CPI report is scheduled for December 10, 2026, covering November 2026.
Households can also follow employment data, wage growth, energy prices and Federal Reserve announcements. These indicators provide additional context for understanding purchasing power and borrowing costs.
Frequently asked questions
What was US inflation in October 2026?
The CPI for All Urban Consumers increased 0.4% in October on a seasonally adjusted monthly basis. The BLS could not publish the usual 12-month percentage change for many October measures because October 2025 survey data were unavailable.
Did food prices increase in October 2026?
Yes. The food index increased 0.5%. Food at home rose 0.4%, while food away from home increased 0.5%.
Does rising inflation always mean interest rates will increase?
No. The Federal Reserve considers several economic indicators, including inflation, employment and broader financial conditions. A single CPI report does not guarantee a rate change.
How can I protect my budget from inflation?
Review actual spending, plan grocery purchases, reduce unused subscriptions, maintain emergency savings and manage high-interest debt.
Final thoughts
The October 2026 inflation report is a useful reminder that household costs can change even when the monthly increase looks relatively small. Food, shelter and energy expenses deserve particular attention because they are difficult for many households to avoid.
Rather than reacting to every headline, review your own spending, adjust your budget where necessary and keep building financial resilience over time. If you are organising your finances from the beginning, start with these personal finance basics.