Roth IRA vs. Traditional IRA: Which Differences Matter Most?
Roth or traditional IRA? Compare 2026 contribution limits, income limits, tax treatment and withdrawal rules — and see which account fits your plan.
Medium risk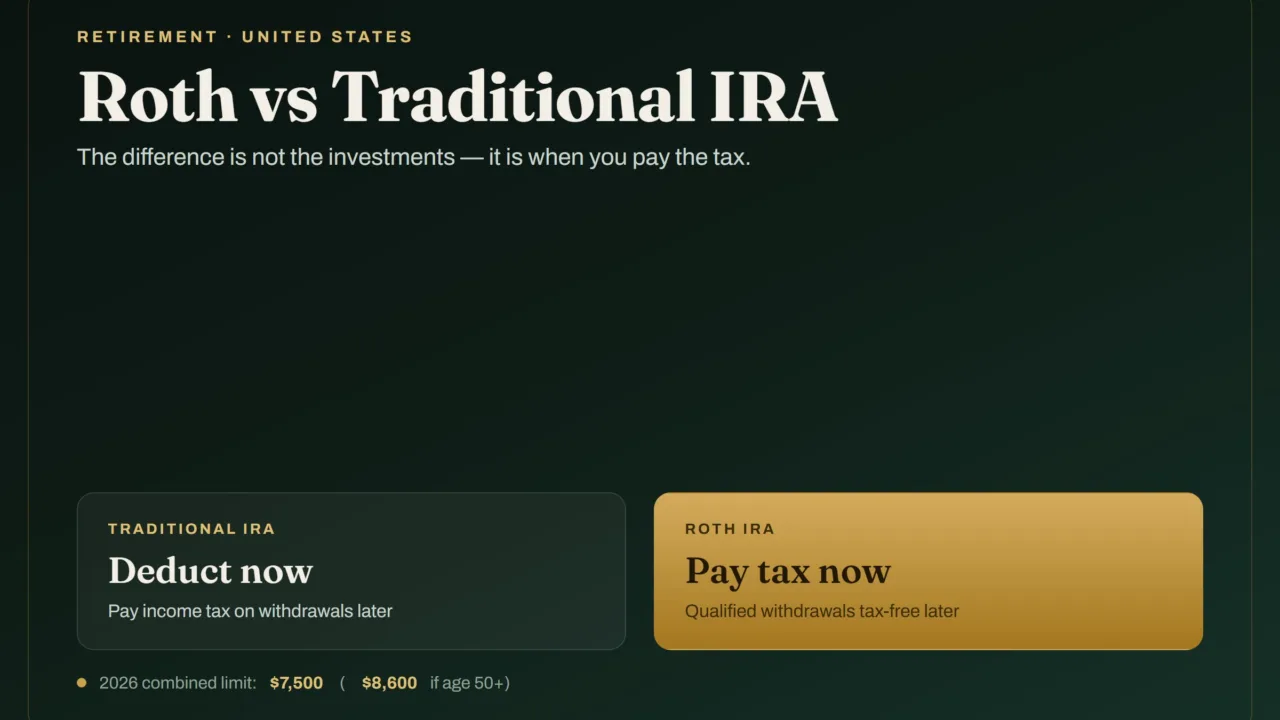
Ask two retirement savers whether a Roth or a traditional IRA is better and you will usually get two confident, opposite answers. In reality, the two accounts are built on the same foundation — they are individual retirement accounts that you open and control yourself — but they sit on opposite sides of one question: do you want the tax benefit today, or in retirement?
That single question drives almost every practical difference between them, from how contributions are treated to whether you face required withdrawals decades from now. This guide works through those differences using 2026 figures, a worked example, and the situations in which each account tends to fit better.
Quick Answer
A traditional IRA may lower your tax bill today, and you pay tax when you take money out. A Roth IRA gives you no deduction today, but qualified withdrawals generally come out tax-free. The two share one combined annual contribution limit — for 2026, $7,500, or $8,600 if you are 50 or older — and the limit applies across all your traditional and Roth IRAs together, not separately. Higher earners can lose the ability to contribute directly to a Roth, and the traditional deduction can shrink with income if you are covered by a workplace plan.
What Is a Traditional IRA?
A traditional IRA is a personal retirement account funded, in many cases, with pre-tax dollars. If you qualify, your contribution reduces your taxable income for the year, so you get a break when you file. The trade-off is that withdrawals in retirement are generally taxable as ordinary income.
The traditional deduction is not automatic for everyone. If neither you nor your spouse is covered by a workplace retirement plan, your contribution is generally deductible in full. If you are covered by a plan at work, the deduction may be limited once your income passes certain thresholds — a detail many savers miss. If the traditional deduction phases out, the account still works; a non-deductible contribution simply behaves more like a Roth, with an after-tax basis tracked on Form 8606 (per IRS Publication 590-A).
What Is a Roth IRA?
A Roth IRA flips the timing. You contribute money you have already paid tax on, receive no deduction this year, and — if you meet the rules — withdraw the money tax-free later. Because the tax is settled up front, growth and qualified withdrawals can compound without a future tax bill hanging over them.
Two features stand out. First, Roth contributions are not subject to required minimum distributions during the original owner’s lifetime, so the money can keep growing untouched (subject to current law). Second, you can withdraw your own contributions at any time, tax- and penalty-free, because you already paid tax on them. Earnings, however, follow stricter rules discussed below.
Roth IRA vs. Traditional IRA: Key Differences
| Feature | Traditional IRA | Roth IRA |
|---|---|---|
| Contribution tax treatment | May be tax-deductible | Not deductible |
| Withdrawal tax treatment | Generally taxable as ordinary income | Generally tax-free if qualified |
| Income eligibility | No income cap to contribute; deduction may phase out | Contribution eligibility phases out at higher incomes |
| Required minimum distributions | Yes, generally from about age 73 | None during the owner’s lifetime |
| Early withdrawal | 10% additional tax before age 59½ unless an exception applies | Same 10% rule on earnings; your own contributions come out tax- and penalty-free |
| Often suits | Those expecting a lower tax rate later | Those expecting a higher tax rate later |
How the Tax Treatment Works
The mechanism is best understood through marginal tax rates. A traditional IRA places the deduction in your peak earning years and the tax bill in retirement, when your taxable income is often lower. A Roth IRA does the reverse: it locks in today’s rate and buys permanent tax-free growth.
If your tax rate falls after you stop working, a traditional IRA can win because you deducted at a high rate and pay tax at a lower one. If your rate rises — through career growth, higher brackets, or future changes in tax law — a Roth can win because you paid a lower rate up front. Because nobody knows future tax rates with certainty, the decision is a judgment call, not a formula.
A Practical Example: Pay Taxes Now or Later?
Suppose you are in the 22% federal bracket and set aside $7,500 for the year. With a traditional IRA, you deduct the full $7,500, cutting this year’s tax by roughly $1,650 (22% × $7,500). With a Roth IRA, you get no deduction and effectively pay that $1,650 now.
One contribution, two tax paths
Assume the $7,500 grows to about $30,000 by retirement. The only difference below is when tax is paid.
| Roth IRA | Withdraw about $30,000 tax-free Tax already paid on the way in |
|---|---|
| Traditional at 22% later | Pay about $6,600 tax, keep about $23,400 |
| Traditional at 12% later | Pay about $3,600 tax, keep about $26,400 |
| Traditional at 32% later | Pay about $9,600 tax, keep about $20,400 |
Why it matters
The comparison is deliberately simplified: it ignores the $1,650 the traditional saver keeps today, which could itself be invested. It also ignores state taxes and any changes in law. The point is not that one account always wins, but that the outcome swings with your future tax rate.
Contribution Limits and Income Eligibility for 2026
The combined limit for 2026 is $7,500, or $8,600 for those age 50 and older (a $1,100 catch-up). This ceiling covers every traditional and Roth IRA you own combined, and it is also capped by your taxable compensation for the year — you cannot contribute more earned income than you have.
For a traditional IRA there is no income ceiling on contributing, but the deduction can phase out for people covered by a workplace plan, with the phase-out beginning at $81,000 for single filers and $129,000 for joint filers in 2026. If you are not covered by a workplace plan, the deduction is generally available in full (limits can still apply if your spouse is covered).
Withdrawal Rules and Potential Penalties
Withdrawals are where the two accounts diverge most sharply in practice. Traditional IRA distributions are generally included in taxable income, and taking money before age 59½ typically triggers a 10% additional tax unless an exception applies (IRS Publication 590-B). Qualified exceptions exist for specific situations such as certain first-home purchases, qualified education expenses, disability, and others — the exact list is worth checking against current IRS guidance.
Roth withdrawals have their own two-part test. To take earnings out tax-free, you generally need to be at least 59½ and have held the Roth for at least five years (the “five-year rule”). Your own contributions are different: since they were made with after-tax money, they can normally be withdrawn at any time without tax or penalty. That extra flexibility is a quiet advantage of the Roth, particularly for someone building early financial resilience.
Which Account May Suit Different Situations?
- You expect a higher tax rate later. A Roth can be attractive, because you settle the tax at today’s lower rate and future withdrawals are tax-free.
- You expect a lower tax rate in retirement. A traditional IRA’s up-front deduction may deliver more value, especially in peak earning years.
- You are early in your career. Lower current income often means a lower marginal rate now, which can favor the Roth.
- You are a high earner covered by a workplace plan. The traditional deduction may be limited, while direct Roth contributions may be unavailable — an important reason to review your options carefully.
- You want flexibility on withdrawals and no lifetime RMDs. The Roth’s design tends to fit better.
- You want to diversify tax exposure. Holding both types gives you a mix of taxable and tax-free income in retirement.
Can You Have Both a Roth IRA and a Traditional IRA?
Yes — and many savers do. You can hold a traditional IRA, a Roth IRA, or both at the same time. The catch is the combined limit: the $7,500 (or $8,600) ceiling is shared, so contributing the maximum to one leaves no room for the other in the same year. Splitting the limit can be a deliberate way to hedge against uncertainty about future tax rates, giving you both a deduction source and a tax-free source later.
Common Mistakes to Avoid
- Treating the limits as separate. The annual cap is combined across all your IRAs.
- Assuming the traditional deduction is automatic. Workplace-plan coverage and income can reduce or eliminate it.
- Ignoring the Roth five-year rule. Withdrawing earnings too soon can cost tax and penalty.
- Contributing without earned income. You need taxable compensation, with limited spousal exceptions.
- Overlooking state taxes. State treatment of contributions and withdrawals can differ from federal rules.
- Chasing a deduction without a plan. A current tax break is only worthwhile if it fits your long-term strategy.
Frequently Asked Questions
Frequently asked questions
What is the 2026 IRA contribution limit?
The combined limit for 2026 is $7,500 across all your traditional and Roth IRAs, or $8,600 if you are age 50 or older. The limit is shared between the two account types and is also capped by your taxable compensation.
Is a Roth IRA or a traditional IRA better?
Neither is universally better. A traditional IRA may help more if you expect a lower tax rate in retirement, while a Roth IRA may help more if you expect a higher rate, want tax-free withdrawals, or value the absence of lifetime required minimum distributions.
Do I have to pay a penalty to withdraw from a Roth IRA?
Your own contributions can generally be withdrawn at any time tax- and penalty-free, because you already paid tax on them. Withdrawing earnings tax-free generally requires being at least 59½ and meeting the five-year rule; otherwise taxes or a 10% additional tax may apply.
Can I contribute to both a Roth and a traditional IRA in the same year?
Yes, but the combined contribution cannot exceed the annual limit. For example, in 2026 you could split $7,500 between the two accounts, as long as your total stays within the cap and any income limits are satisfied.
Do traditional IRAs require minimum withdrawals?
Yes. Traditional IRAs are generally subject to required minimum distributions beginning around age 73 under current law. Roth IRAs are not subject to lifetime required minimum distributions for the original account owner.
Is the traditional IRA deduction always available?
No. If you or your spouse is covered by a workplace retirement plan, the deduction can phase out above certain income levels. If neither of you is covered, the contribution is generally fully deductible.
Conclusion
The Roth versus traditional IRA choice is really a wager on your future tax rate — one that nobody can call with certainty. What you can control is how you think about it. If today’s rate looks low relative to tomorrow’s, a Roth can lock in that advantage and add flexibility along the way. If today’s rate looks high and retirement income will be lower, the traditional deduction may be worth more.
Used together, the two accounts let you hedge. The most valuable step is not choosing one at all costs, but understanding your own tax picture well enough to make the choice deliberately — then reviewing it as your income, goals and the rules evolve.
Sources
- IRS — Roth IRAs Internal Revenue Service
- IRS — Retirement topics: IRA contribution limits Internal Revenue Service
- IRS — COLA increases for dollar limitations on benefits and contributions (2026 limits) Internal Revenue Service
- IRS — Publication 590-A, Contributions to Individual Retirement Arrangements (IRAs) Internal Revenue Service
- IRS — Publication 590-B, Distributions from Individual Retirement Arrangements (IRAs) Internal Revenue Service
Disclaimer
This article is general educational information, not personalized financial, tax, investment or legal advice. IRS contribution limits, income phase-outs and rules can change, and your circumstances may differ. Verify current figures with the IRS or a qualified tax professional before making decisions about a Roth or traditional IRA.
Related articles
How Much House Can You Afford on a $75,000 Salary?
Earning $75,000 a year? See how much house you may afford, how to estimate the monthly mortgage payment, plan a down payment and avoid common homebuying…

Gold in 2026: Buy Now or Wait?
Should you buy gold now or wait? A look at the 2026 gold outlook, the forces moving prices, and a practical approach to buying without trying…
Index Funds vs. Individual Stocks: Which Is Better for Beginner Investors?
Compare index funds and individual stocks for beginners — diversification, risk, costs, research and what to consider before you invest.