How Much House Can You Afford on a $75,000 Salary?
Earning $75,000 a year? See how much house you may afford, how to estimate the monthly mortgage payment, plan a down payment and avoid common homebuying mistakes.
Medium risk
Buying a home on a $75,000 salary may be possible, but the price you can comfortably afford depends on more than your annual income. Your existing debts, savings, credit profile, mortgage rate and local housing costs all influence the decision.
A home that fits comfortably into one person’s budget could leave another buyer struggling to cover ordinary expenses. That is why it helps to work backward from a realistic monthly payment instead of starting with the most expensive property a lender might approve.
If you earn $75,000 a year, your gross monthly income is $6,250. That gives you a useful starting point for estimating affordability, although the amount deposited into your bank account will be lower after taxes and other payroll deductions.
What Price Range Should You Consider on a $75,000 Salary?
A reasonable starting point is to examine how much of your monthly income could go toward housing. A commonly used guideline suggests keeping total monthly housing expenses around 28% of gross income. On a $75,000 salary, that works out to approximately $1,750 per month.
$1,750
Illustrative monthly housing budget (28% of gross)
Based on a $75,000 salary ($6,250 monthly gross). A budgeting guideline, not a guarantee that a mortgage is affordable.
Illustrative example, not a guarantee.
However, this is a budgeting guideline, not a guarantee that a particular mortgage is affordable. Your other debts and living expenses may require a lower housing budget.
Also, the $1,750 figure must cover more than the mortgage’s principal and interest. Property taxes, homeowners insurance and potentially private mortgage insurance (PMI) or homeowners association (HOA) fees need to be considered.
A Realistic Monthly Mortgage Example
Suppose you earn $75,000 annually, have manageable debt and want to purchase a home with a 30-year fixed-rate mortgage. Here is an illustrative example of how the numbers might work.
| Item | Example |
|---|---|
| Annual gross income | $75,000 |
| Monthly gross income | $6,250 |
| Illustrative monthly housing budget | $1,750 |
| Estimated principal and interest allowance | $1,250–$1,300 |
| Remaining for taxes, insurance and other housing charges | $450–$500 |
These figures are planning estimates, not a lender quote. Actual property taxes and insurance premiums can vary substantially by location.
For context, Freddie Mac’s average 30-year fixed mortgage rate was reported at 7.40% on October 8, 2026. At that rate, a $180,000 mortgage would have principal-and-interest payments of roughly $1,245 per month over 30 years, before taxes, insurance and other charges.
How Much Down Payment Do You Need?
Your down payment affects both the amount you borrow and your ongoing housing costs. For example, consider a hypothetical $200,000 home.
Down payment on a $200,000 home
| 10% down | $20,000 down, borrow $180,000 |
|---|---|
| 20% down | $40,000 down, borrow $160,000 |
Why it matters
The larger down payment reduces the loan amount and may eliminate the need for PMI on a conventional mortgage. But putting more money down is not always the best choice if it leaves you without enough savings for emergencies, closing costs or repairs.
Remember that the down payment is not the only upfront expense. Closing costs, inspections, moving expenses and initial home repairs may require additional cash.
Four Expenses Buyers Often Underestimate
1. Property taxes
Property taxes depend on the location and the property’s assessed value. Two homes with similar purchase prices can have different annual tax bills. Before making an offer, look up the property’s current taxes and ask whether a reassessment after purchase could change the amount.
2. Homeowners insurance
Insurance protects against certain covered losses and is generally required by mortgage lenders. Premiums can differ significantly depending on the property, location and coverage. Homes in areas exposed to hurricanes, wildfires or flooding may involve additional insurance considerations.
3. Private mortgage insurance
If you make a smaller down payment on a conventional mortgage, you may need PMI. This additional expense can make a seemingly affordable loan more expensive each month. Ask the lender for an estimate of the full payment, including any required mortgage insurance.
4. Maintenance and repairs
Owning a home means paying for repairs that a landlord might otherwise handle. A broken appliance, plumbing issue or roof repair can disrupt a budget that has no room for unexpected expenses. Keep money available for home maintenance instead of using every available dollar toward the purchase.
Does Your Existing Debt Change How Much You Can Afford?
Absolutely. A $75,000 salary does not tell the whole story if you also have student loans, car payments or credit card balances.
Imagine two buyers with identical incomes. One has $200 in monthly debt payments, while the other pays $900. The second buyer has less room in the budget for housing, even though their salaries are the same.
Mortgage lenders commonly assess debt-to-income ratio, which compares monthly debt obligations with gross monthly income. But passing a lender’s affordability assessment does not automatically mean the payment will feel comfortable in everyday life. Your own budget should also leave room for groceries, transportation, healthcare, retirement contributions and other financial priorities.
How to Estimate Your Own Home Budget
Before browsing listings, take these steps:
- Calculate your actual monthly take-home pay.
- List existing loan payments and recurring household expenses.
- Decide how much you can spend on total housing costs without sacrificing essential savings.
- Estimate property taxes, homeowners insurance, PMI and HOA fees for homes in your preferred area.
- Check mortgage rates and compare written loan estimates from multiple lenders.
- Keep enough savings for emergencies, closing costs and future repairs.
A mortgage calculator can help you test different loan amounts, down payments and interest rates. Change one variable at a time to understand how the payment responds.
The Bottom Line
A $75,000 salary can provide a starting point for buying a home, but it does not determine a single affordable purchase price. Your location, existing debts, available savings and mortgage terms all matter.
An illustrative housing budget of around $1,750 per month may be a useful starting point for someone earning $75,000 annually, but some buyers will need to spend less. In higher-cost areas, purchasing may require a larger down payment, a less expensive property or more time to save.
The best home is not necessarily the most expensive one you qualify for. It is the one whose ongoing costs fit your budget while leaving enough room for emergencies, everyday life and your other financial goals.
Frequently asked questions
How much house can I afford on a $75,000 salary?
A common guideline is to keep total housing costs around 28% of gross income, which is about $1,750 a month on a $75,000 salary. The actual price depends on your debts, down payment, mortgage rate and local taxes and insurance.
What monthly mortgage payment can I afford on $75,000?
Around $1,750 a month for total housing costs is a common starting guideline, but your other debts and savings may require a lower payment. The figure must include taxes, insurance and any mortgage insurance.
How much down payment do I need to buy a house?
Many buyers put down between 5% and 20%. On a $200,000 home, 10% is $20,000 and 20% is $40,000. A larger down payment lowers the loan and may remove PMI, but keep cash available for emergencies, closing costs and repairs.
Does existing debt affect how much house I can afford?
Yes. Lenders assess your debt-to-income ratio, and higher monthly debt payments reduce the housing payment you can comfortably support. Two buyers on the same salary can afford different amounts.
Sources
Disclaimer
This article provides general educational information, not personalized mortgage, financial, tax or legal advice. Mortgage rates and housing costs change. Verify current rates, property taxes, insurance costs and loan terms before making a home purchase.
Related articles
Gold in 2026: Buy Now or Wait?
Should you buy gold now or wait? A look at the 2026 gold outlook, the forces moving prices, and a practical approach to buying without trying…

Index Funds vs. Individual Stocks: Which Is Better for Beginner Investors?
Compare index funds and individual stocks for beginners — diversification, risk, costs, research and what to consider before you invest.
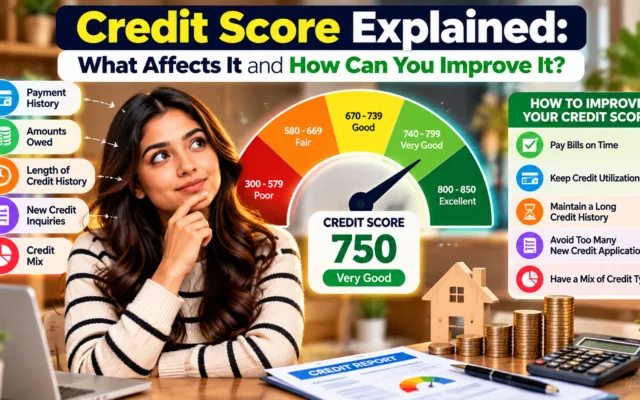
Credit Score Explained: What Affects It and How Can You Improve It?
Learn what a credit score is, which habits and factors can affect it, and practical steps to build and maintain a healthier credit profile.